Industry Trends
CarGurus Intelligence Report - October 2026
Used: Inventory Hits Post-COVID High, but Affordable Supply Stays Tight
The used inventory rebound accelerated in October in line with the traditional seasonal boost, up 4.8% year-over-year (YoY) and 2.2% month-over-month (MoM). Overall used days supply is flat against last year at 50.4, indicating the market is absorbing the extra inventory.
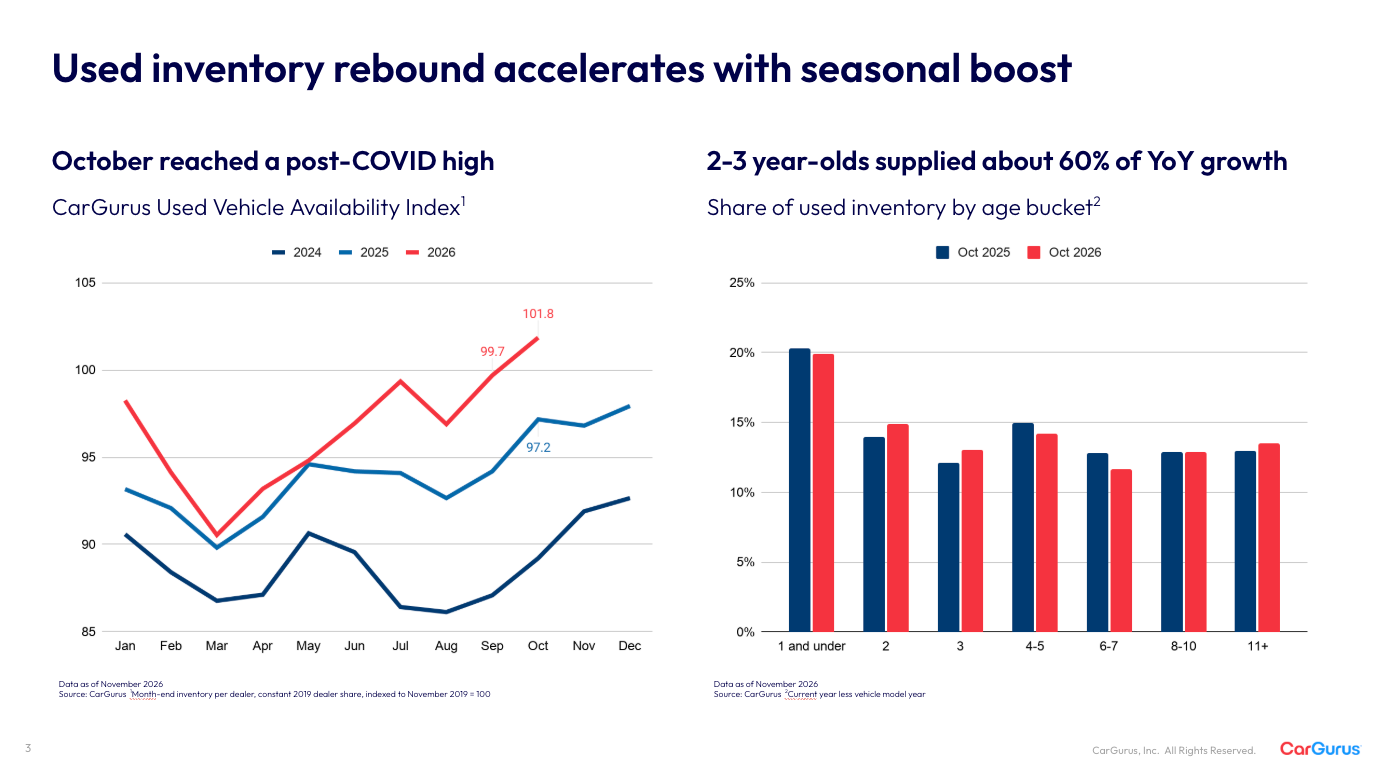
Nearly new used models (3 years and younger) did most of the work, supplying about 60% of the YoY increase. This suggests that the anticipated increase in off-lease vehicles on lots may have arrived and recovery from the chip shortage should accelerate, making up for the depressed inventory in 4- to 7-year-old vehicles, the model years most affected by the chip shortage.
The average used listing price fell below $30,000 for the first time in six months to an average of $29.8k, down 0.7% from September and 1.4% from the $30.2k peak in August. Even after the decline, the average price is still $985 higher than a year ago. What’s causing this? Affordability keeps getting squeezed: the share of used listings priced under $15k fell 3% YoY while total inventory grew about 5%. That lower-priced tier also had the tightest market days supply, at about 49 days compared to over 60 days for $50K+.
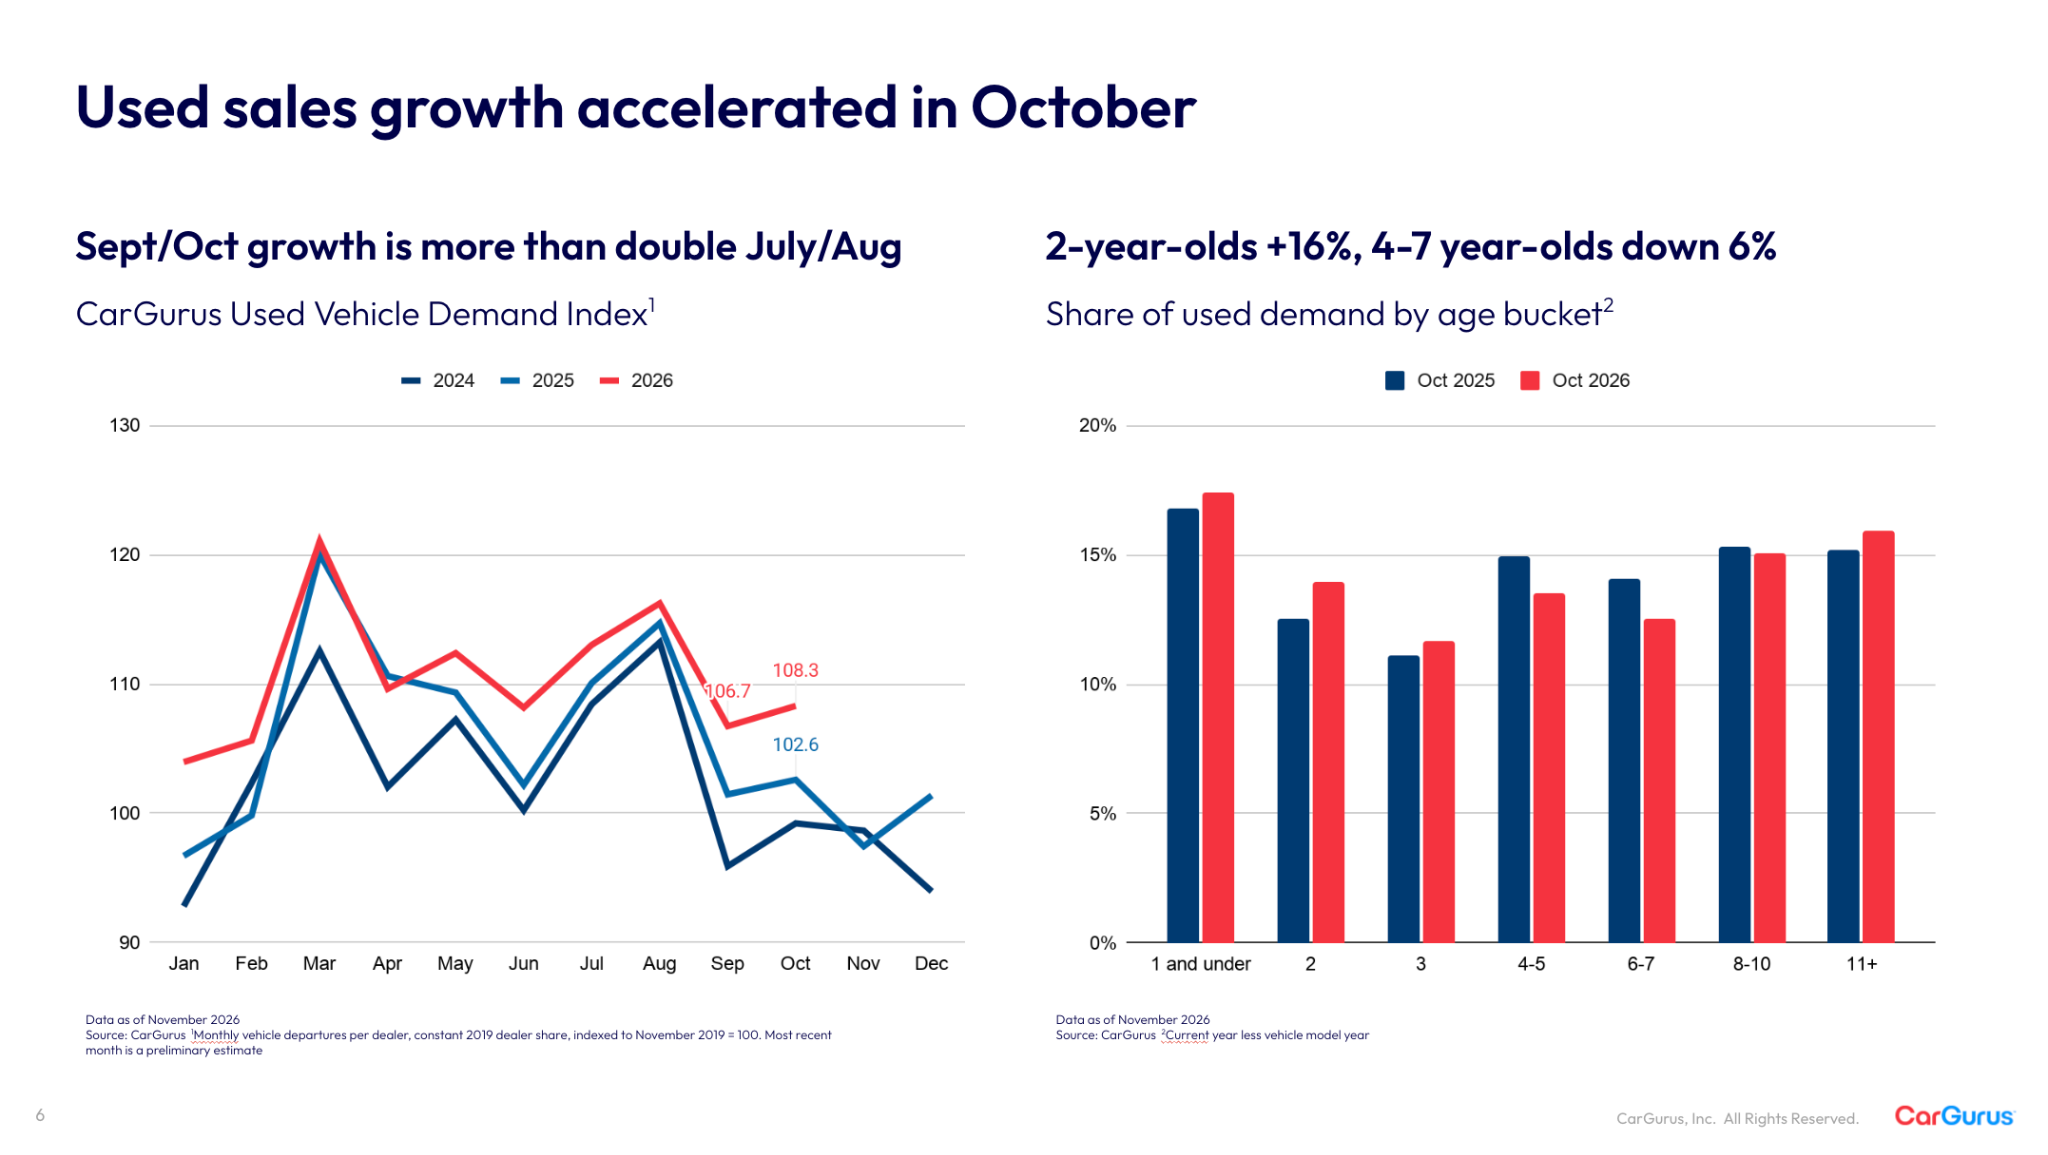
Demand held up, with the youngest cars out in front, suggesting those being priced out of new are continuing to gravitate to the growing off-lease supply on the used market. Used demand is estimated at 5.6% above last October, with the nearly new segment running 11% above year-ago levels. Underscoring this demand, 3-year-old and younger models made up 43% of sales in October, up from 40.4% last year. Sales are following supply, with 2-year-old sales up 16% against a 13% rise in listings.
Time on lot is the softer spot. Average days on market rose 2.1 days in October to 70.9, level with last year after six straight monthly increases. The 3-day cushion the market held over 2025 through the summer is nearly gone due to a 3% YoY increase in Franchise days on market, offsetting declines from Independents. Listings on the lot for 60 days or more made up 36% of used inventory, up two percentage points year over year.
New: Inventory Rebuilds, but Not Where Demand Is
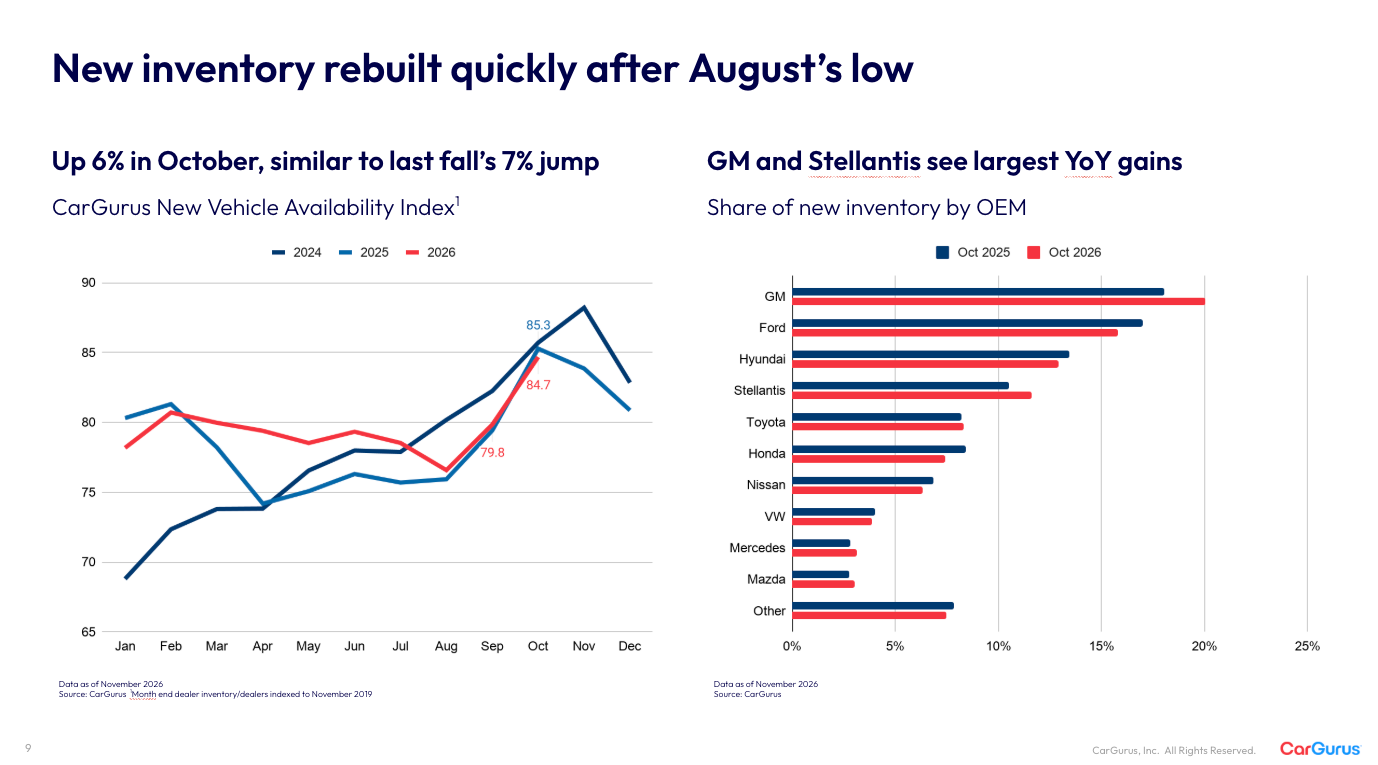
New inventory rebuilt quickly in October, up 6% from September after bottoming out in August. Although the rebuild is nearly on par with 2025 levels, it wasn't evenly spread. GM and Stellantis each added roughly 10% more units than a year ago, while Ford and Honda saw declines of 8% and 13% respectively.
Average new listing prices slipped 0.5% from September to $51.6k, the first monthly decline this year, but they're still up 4.3% YoY. Mix keeps pushing the average up. The share of new listings under $40k are down 12% YoY, while listings at $50k and above are up 17% and now make up 45% of inventory, from 40% a year ago.
New retail demand is estimated at 1.2% above last October, a running 2026 trend as only 4 months so far this year posted gains above year-ago levels. The Detroit Three hold about 47% of new inventory but only about 35% of sales. Stellantis sits at 122 average days on market, 35 more than last year, while Toyota holds 8% of inventory and 21% of sales and its vehicles sit about 40 days.
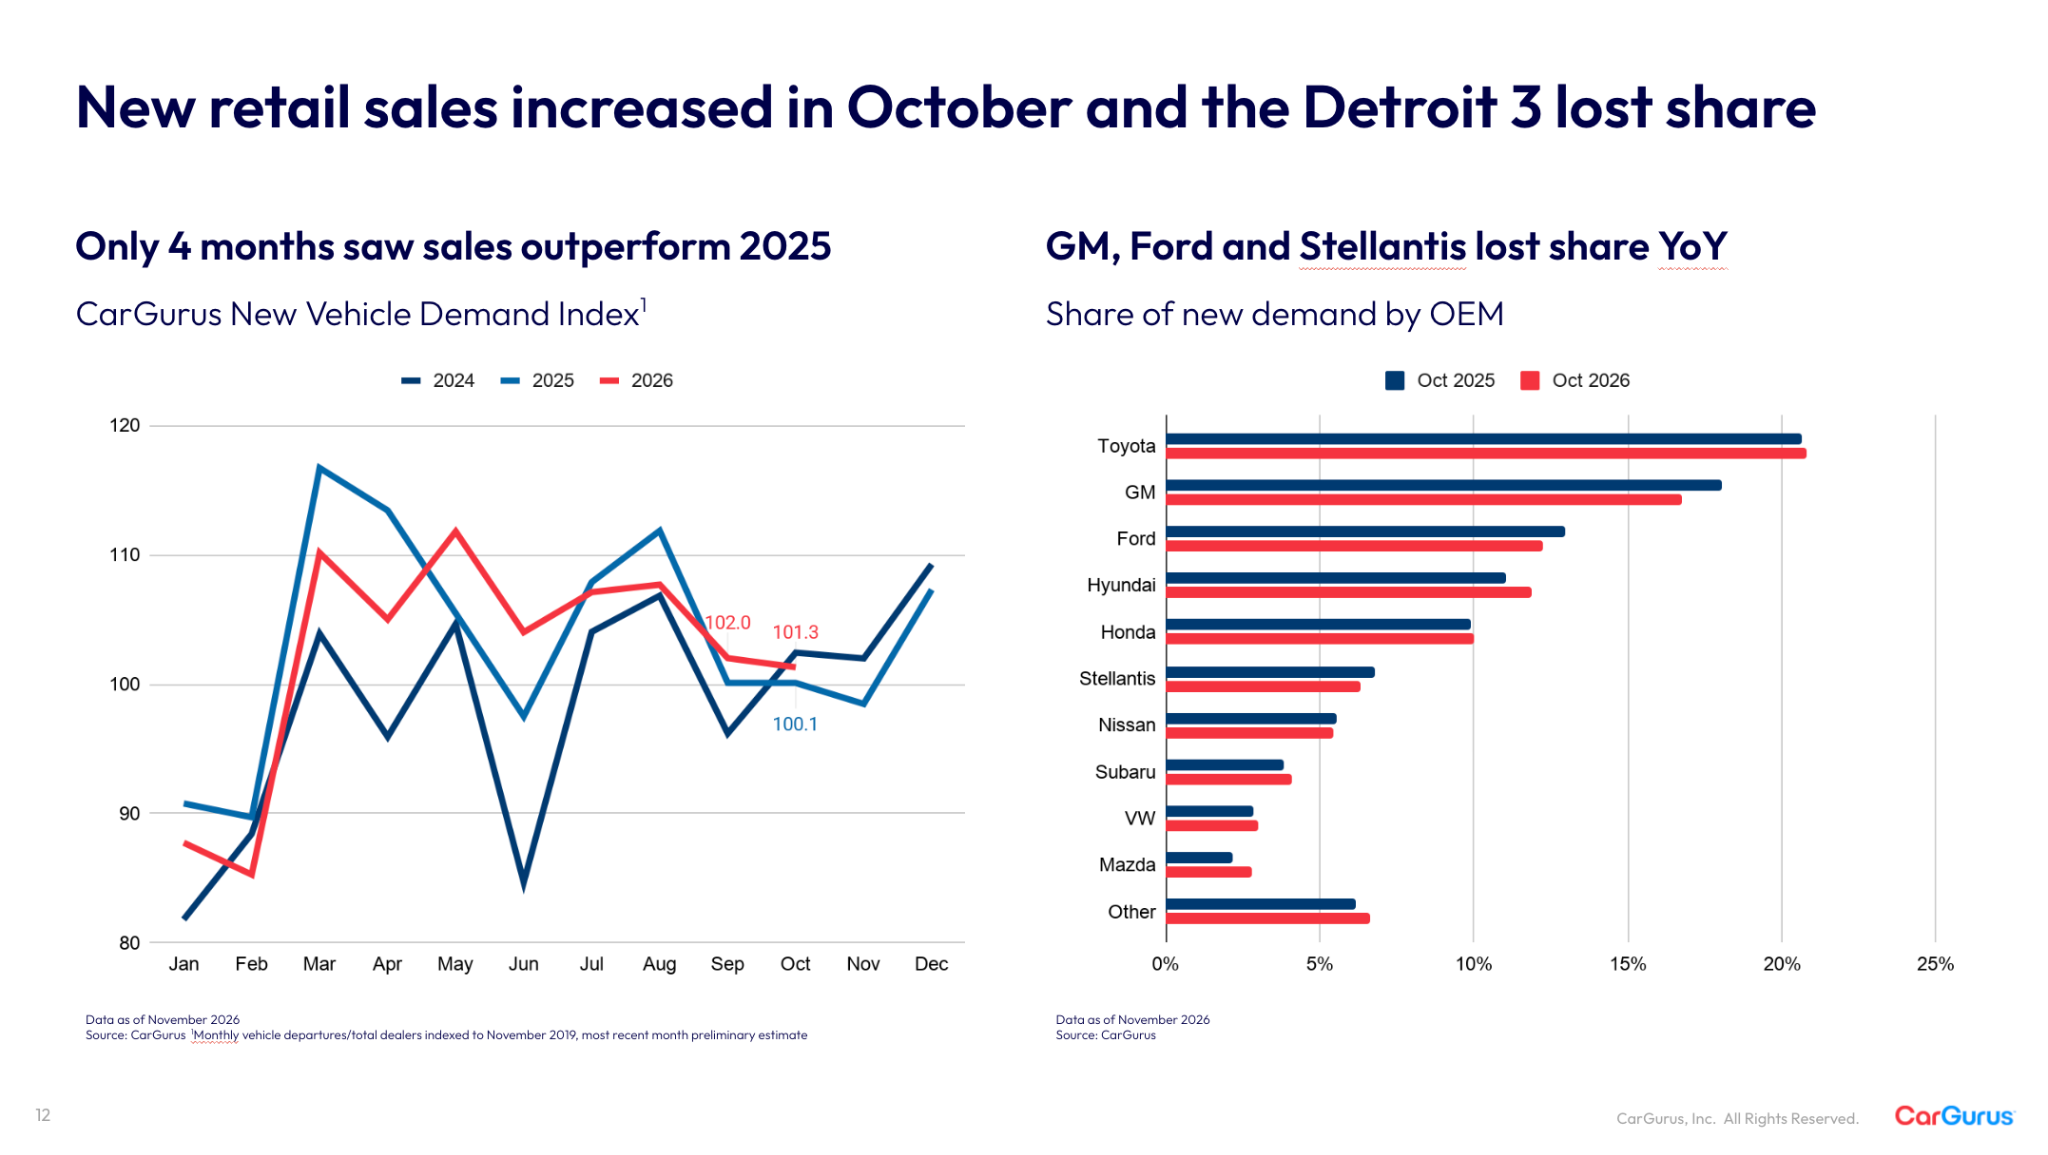
Overall, new days supply of 79.8 is flat against last year, but that hides a split. Vehicles under $50k had 4 to 8 fewer days of supply than a year ago, while vehicles at $70k and above have 11 to 12 more, at roughly 99 days. Affordable vehicles are selling faster, and the stock is building in the segments that aren't. OEMs may have to look to incentives towards the end of the year to better balance inventory.